Rupee Under Pressure: RBI’s China Playbook
Recently, the RBI has adopted a strategy like one used by China to manage currency risks. The objective is to make certain foreign exchange transactions more expensive, discourage excessive demand for US dollars, and give the rupee some breathing room. It means that RBI is taking actions to stop people, businesses, and investors from buying too many US dollars (USD).
The Indian rupee has been under pressure, prompting the Reserve Bank of India (RBI) to introduce a fresh set of measures to stabilize the currency. Despite a 25-basis-point hike in the policy repo rate recently, the rupee continued to face downward pressure.
China’s Currency Strategy: What Is the Connection?
China has previously used its Foreign Exchange Risk Reserve Ratio (FERR) to influence activity in the foreign exchange market. In March, China reduced this ratio from 20% to zero. The move made it less costly for market participants to take positions against the yuan, at a time when the Chinese currency was facing appreciation pressure against the US dollar.
India is facing a different situation.
The rupee is under depreciation pressure, and the RBI is using a similar policy instrument in the opposite direction to discourage excessive demand for dollar-related positions. The broader lesson is that central banks can adjust the cost of foreign exchange transactions depending on the direction of pressure on their currencies.
China's decision was intended to ease pressure associated with a strengthening yuan. India's measure is intended to help manage pressure on a weakening rupee.
What Is RBI’s Foreign Exchange Risk Reserve (FERR)?
One of the notable measures announced by the RBI is the introduction of a Foreign Exchange Risk Reserve (FERR) requirement for certain rupee-linked foreign exchange derivative contracts.
Under the measure described in the announcement, banks must maintain a reserve equivalent to 20% of the value of specified forex derivative contracts exceeding $2 million that involve the rupee, subject to the RBI’s prescribed rules and any subsequent changes to the percentage.
The reserve is to be maintained in cash with the RBI. In simple terms, banks will have to set aside additional money when entering into the covered transactions. This increases the cost of certain foreign exchange positions and may discourage excessive speculative activity.
Why Is the Indian Rupee Falling Against the US Dollar?
The rupee’s weakness is linked to several factors, including India’s trade deficit, demand for dollars, foreign investment flows, and global economic uncertainty. India imports significant quantities of crude oil, electronics, machinery, and other goods. Many of these purchases are paid for in US dollars. When Indian importers need more dollars, demand for the US currency rises.
If demand for dollars increases faster than its supply, the dollar becomes more expensive in rupee terms, putting downward pressure on the Indian currency. Other factors can add to this pressure:
- Trade deficit: India spends more on imports than it earns from exports, creating demand for foreign currency.
- Crude oil prices: Higher oil prices increase India’s import bill and its demand for dollars.
- Foreign investment outflows: When foreign investors withdraw money from Indian markets, they may convert their rupee holdings into dollars.
- Currency hedging: Businesses and financial institutions may increase their demand for protection against a weaker rupee, influencing activity in the foreign exchange market.
The RBI’s challenge is to manage these pressures without unnecessarily disrupting legitimate international trade and investment.
Why Is the RBI Making Currency Hedging More Expensive?
At first glance, this move may seem counterproductive.
Businesses routinely use currency hedging to protect themselves against exchange rate fluctuations. For example, an Indian company importing machinery from the United States may worry that the rupee will weaken before payment is due.
If the rupee depreciates, the company will need more rupees to purchase the same amount of dollars. By using a suitable financial contract, it can reduce uncertainty about its future payment. Hedging is therefore an important risk-management tool.
However, when many market participants simultaneously seek protection against a falling rupee, their transactions can add to demand for dollar-linked contracts and intensify pressure in parts of the foreign exchange market. The RBI’s approach is to increase the cost of certain transactions, particularly those that may contribute to excessive speculative demand.
The distinction is important: the policy does not eliminate the need for legitimate hedging; it seeks to influence the cost and scale of specified foreign exchange transactions.
How Does a Trade Deficit Weaken the Rupee?
A trade deficit occurs when a country's imports exceed its exports.
For India, a sustained trade deficit can create additional demand for foreign currencies because importers need to pay overseas suppliers. Exporters, in contrast, bring foreign currency into the country when they receive payments from abroad.
The resulting pressure on the rupee depends on more than the trade balance alone. Capital flows, service exports, remittances, foreign investment, and central bank intervention also influence the exchange rate.
For example, strong foreign investment inflows can help offset the demand for dollars generated by imports. Conversely, large capital outflows can intensify depreciation pressure.
India has also been exploring ways to settle more international trade in rupees and other national currencies. Such arrangements can reduce dependence on the dollar in eligible transactions, although they cannot eliminate India's overall foreign exchange requirements.
RBI's Other Measures to Stabilize the Rupee
Apart from the Foreign Exchange Risk Reserve, RBI has taken 4 other steps:
1. Centralized dollar buying for oil PSUs: RBI will route dollar purchases of IOC, BPCL, and HPCL through one channel. This helps monitor the timing of demand and supply dollars from reserves to avoid sudden spikes.
2. Ban on rebooking cancelled rupee derivatives: Companies can't cancel and rebook certain rupee derivative contracts to build speculative positions. This reduces extra pressure on the rupee.
3. No double hedging: One genuine exposure (like a dollar payment) cannot be used to take multiple overlapping hedges. This stops firms from creating positions beyond actual business needs.
4. Stricter asset verification: For using assets as underlying for hedging, proof is now needed for exposures above $5 million, down from the earlier $100 million limit. This tightens checks and prevents misuse of derivatives.
Why Did Rupee Fall Despite Repo Rate Hike?
On Oct 7, RBI hiked the repo rate by 25 bps to 5.5%, but the rupee remained weak. Normally, higher rates support currency by attracting investors, but it is not automatic. The rupee is also driven by global rates, investor sentiment, oil prices, dollar demand, and growth expectations; a rate hike alone can't offset these. Liquidity also matters.
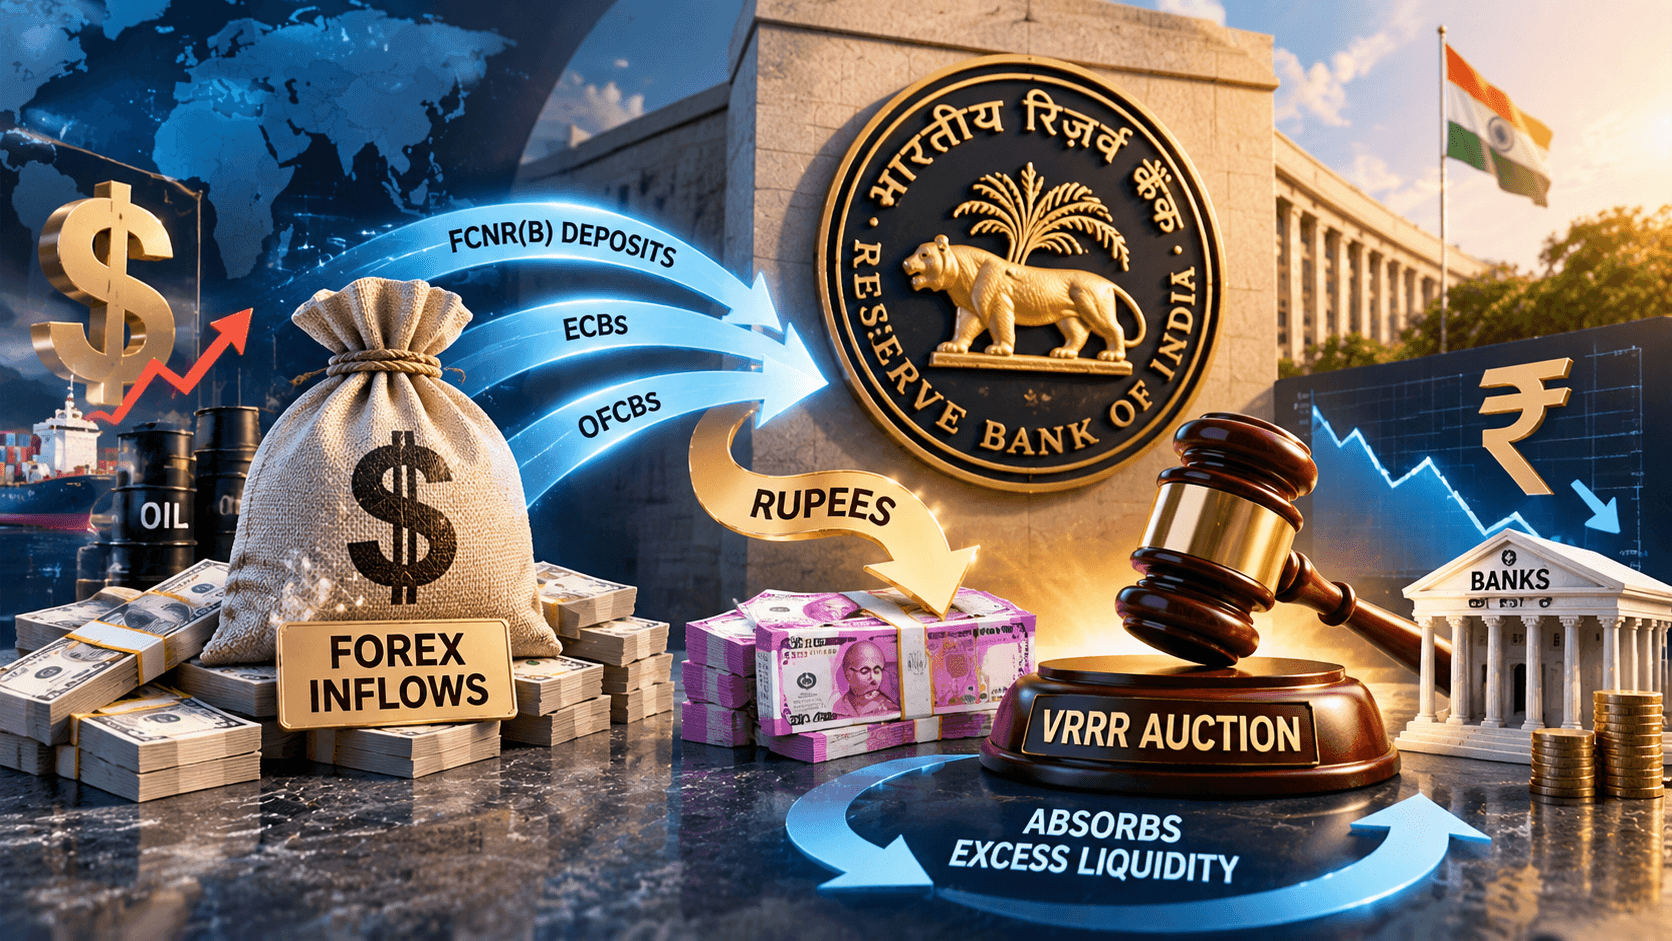
In June, RBI opened a concessional swap window for FCNR(B) deposits to attract forex, which added rupee liquidity. When banks have surplus liquidity, RBI uses tools to absorb it. So, the latest forex measures are part of a larger effort to manage both currency pressure and domestic liquidity.
Is RBI Repeating the 2013 Taper Tantrum Strategy?
In 2013, expectations of the US Fed tapering its bond-buying triggered volatility; emerging currencies, including the rupee, fell sharply as investors pulled out, raising India's external financing worries.
The current steps show similar concern about excessive dollar demand. By centralizing oil PSUs' dollar buying and tightening derivative rules, RBI is trying to curb pressure and avoid disorderly moves. The difference is that circumstances are not identical. These measures are meant to buy time and stabilize the market, not to fix the root economic causes of rupee depreciation.
Conclusion:
The RBI's adoption of a China-style foreign exchange risk reserve mechanism highlights how central banks use regulatory tools to influence currency markets. By raising the cost of certain rupee-linked derivative transactions, tightening hedging rules and managing large dollar purchases, the RBI is seeking to reduce excessive demand for foreign currency and limit pressure on the rupee. However, currency management is not simply about restricting transactions. India's import dependence, oil prices, capital flows, and global financial conditions will continue to shape the rupee's performance.
Reference: